
As the Federal Reserve resumed rate hikes in September and the 10-year Treasury yield surpassed 5%, its highest level since 2007, investors may be wondering how persistently higher interest rates could reshape asset prices. While rising yields have created challenges for traditional fixed income sectors, syndicated bank loans have been a bright spot according to a recent quarterly markets commentary from Morningstar Indexes Strategist Dan Lefkovitz.
The Morningstar US Core Bond Index declined by 2.7% for the first three quarters of 2026. Longer-duration Treasuries, represented by the Morningstar US 10+ Year Treasury Bond Index, lost 7.2% over the same period. Meanwhile, bank loans have benefited from the recent Fed activity due to their floating-rate coupon structure. The asset class, measured by the Morningstar LSTA US Leveraged Loan Index, has gained 3.3% for the year to date.
Rising Bond Yields Pummel Interest Rate-Sensitive Fixed Income in 2026, While Floating-Rate Loans Benefit
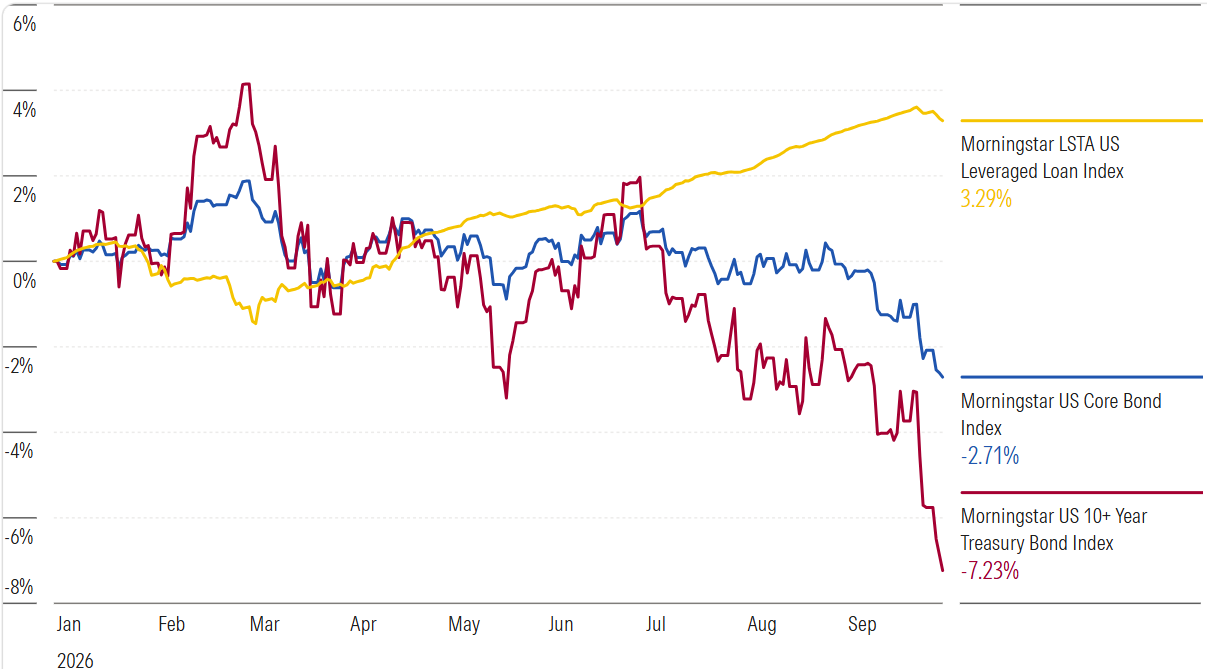
Source: Morningstar Direct. Data as of September 30, 2026. Total returns in USD for Morningstar Indexes.
Elizabeth Templeton, Senior Fixed Income & Multi-Asset Product Manager at Morningstar Indexes, said:
“In an environment where higher rates can create challenges for interest rate-sensitive fixed income sectors, leveraged loans have demonstrated the potential benefits of floating-rate exposure, helping investors reduce interest rate sensitivity. For investors seeking diversification across fixed income markets, this may be an opportune time to evaluate whether bank loans can have a role in their portfolios.”
©2026 Morningstar. All Rights Reserved. The information, data, analyses and opinions contained herein (1) include the proprietary information of Morningstar, (2) may not be copied or redistributed, (3) do not constitute investment advice offered by Morningstar, (4) are provided solely for informational purposes and therefore are not an offer to buy or sell a security, and (5) are not warranted to be correct, complete or accurate. Morningstar has not given its consent to be deemed an "expert" under the federal Securities Act of 1933. Except as otherwise required by law, Morningstar is not responsible for any trading decisions, damages or other losses resulting from, or related to, this information, data, analyses or opinions or their use. References to specific securities or other investment options should not be considered an offer (as defined by the Securities and Exchange Act) to purchase or sell that specific investment. Past performance does not guarantee future results. Before making any investment decision, consider if the investment is suitable for you by referencing your own financial position, investment objectives, and risk profile. Always consult with your financial advisor before investing.
Indexes are unmanaged and not available for direct investment.
Morningstar indexes are created and maintained by Morningstar, Inc. Morningstar® is a registered trademark of Morningstar, Inc.